Introduction
Digital financial services have changed the way people borrow money, and for many households the change has been enormous. Not so long ago, getting a loan meant taking a morning off work, queuing at a bank branch and filling in pages of forms across a desk from someone in a suit. Today, a borrower can compare loan options, send off an application and track its progress on a phone while sitting on the sofa after the children have gone to bed. That convenience is genuinely useful. It isn’t the only thing that matters, though. Repayment obligations, interest rates, eligibility rules and security measures all deserve just as much attention as the speed of the process. Quick money can solve a problem. The wrong loan can quietly create a bigger one.
Fast online loans can help when life throws an unexpected bill on the table, such as a dentist’s fee for a cracked tooth on a Saturday or a laptop that gives up the week before a university deadline. Careful financial planning still matters just as much as how quickly the money arrives. People who understand how the application process works, and who take a little time to compare their options, are far more likely to end up with credit that suits their lives rather than squeezing them.
How Online Loan Applications Work
Online lending usually starts with an application on a digital platform. Applicants share basic personal details, information about their income and whatever documents the lender needs to judge their eligibility. Depending on the lender and the type of loan, identity checks and further financial reviews may come next. For someone already stressed about money, the list of questions can feel endless. Each one exists for a reason, though, because it helps the lender decide whether the loan is realistic for that person.
Once the application lands, the lender looks over the information and decides whether the applicant meets its criteria. Some platforms reply surprisingly quickly, while others take longer, depending on their verification steps, how accurate the application is and each person’s situation. A single wrong digit in a bank account number can turn a same-day answer into three days of confused emails. Taking an extra minute to double-check every field often saves a great deal of waiting.
The process can be a real help for people who simply can’t get to a bank during opening hours, such as nurses on night shifts or parents juggling school runs and work. An online application still isn’t a promise of approval, though, and whether money becomes available depends on the lender’s policies and the applicant’s qualifications. Pressing “submit” is the beginning of the process, not the end of it.
Understanding Fast and Secure Loans
The phrase prestamos rápidos y seguros refers to fast and secure loans, an option that attracts borrowers who want timely access to credit without needless complications. Speed and security are two very different things, though, and having one doesn’t guarantee the other. A loan can arrive in minutes and still turn out to be a poor deal.
A fast loan comes from an efficient application and assessment process. A secure loan depends on careful protection of personal information, clear contractual terms and responsible lending. A service that offers rapid decisions still owes applicants enough information to understand exactly what they’re agreeing to. A decision in five minutes sounds impressive. A contract that a person can actually understand in five minutes is even more impressive, and far rarer.
Before handing over any sensitive information, it pays to confirm the lender’s legal identity, read its privacy policy and go through the terms properly. A legitimate lender sets out its costs, repayment schedule and the consequences of a missed payment in plain, everyday language. When those details are buried in tiny print or missing altogether, that silence says a great deal.
Applying for Loans Through a Mobile Phone
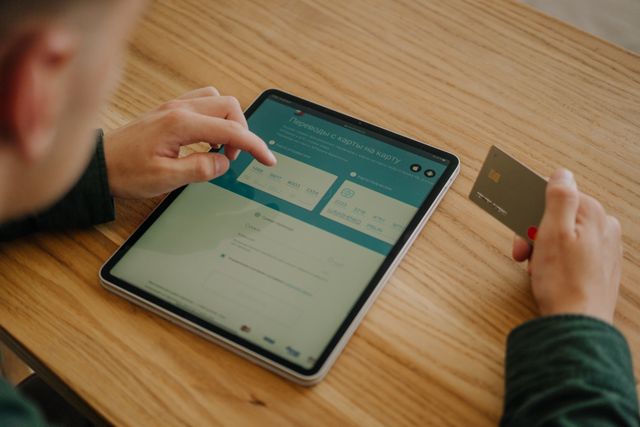
Mobile technology has made digital borrowing far more accessible. Many lending platforms let applicants fill in forms, upload photos of documents and check on their application straight from a smartphone, whether they’re waiting for a bus, sitting in a doctor’s waiting room or on a lunch break at work.
The general process often involves several steps:
- Reviewing the available loan products and eligibility requirements.
- Entering accurate personal and financial information.
- Completing any required identity verification.
- Examining the proposed loan amount, total cost and repayment dates.
- Accepting the agreement only after understanding its conditions.
The instruction “Solicita desde tu celular prestamos rápidos y seguros” highlights the convenience of starting a loan application on a mobile device. That convenience is at its best when it comes with a healthy dose of care, which means making sure the service is genuine and the agreement is fully understood before going any further. Tapping “accept” takes less than a second. The agreement that follows may last for many months.
A secure internet connection, an up-to-date phone and caution with verification codes all reduce the most common digital risks. Applying for a loan over free café Wi-Fi isn’t ideal, and reading a one-time code aloud to a caller who claims to be “from the lender” is a mistake that scammers count on. A real lender never needs that code from a phone call.
Evaluating Interest Rates and Total Borrowing Costs
Interest rates matter, but they never tell the whole story. Extra charges, administrative fees, late-payment penalties and other costs can all push up the final amount that has to be repaid. The big, friendly number on an advert is rarely the number that eventually leaves a borrower’s bank account.
Looking at the total repayment amount gives a much more honest picture than focusing on the advertised rate or the speed of approval. The timing of payments matters just as much. A repayment due on the 20th of each month is a constant headache for someone whose wages don’t arrive until the 28th, however modest the amount looks on paper. A loan that fits the calendar is far easier to live with than one that fights it.
A loan with comfortable monthly payments can still end up expensive if it stretches over a long period or picks up extra charges along the way. Small payments feel kind at first. Paying them for twice as long often doesn’t. Reading the full agreement, rather than just the summary on the first screen, helps borrowers avoid nasty surprises and judge whether the loan is truly affordable.
Recognizing Potential Online Lending Scams
Online lending calls for a sharp eye when it comes to fraud. Scammers may pose as well-known financial institutions, promise approval to absolutely everyone or pressure people into making an instant decision. A message congratulating someone on a “pre-approved” loan they never applied for is one of the oldest tricks around, and it still catches people out.
Warning signs include vague company details, missing contract information, requests for sensitive data that has nothing to do with the loan and demands for upfront payments in odd circumstances. No genuine lender asks for a “processing fee” paid in gift cards or through a stranger’s personal account. Checking a provider’s registration and contact details through proper official sources is one of the simplest and most effective protections there is.
Passwords, identity documents and banking details belong nowhere near unverified messages, however friendly, official or urgent they sound. An offer posted by a stranger in a social media group, promising easy money to anyone who sends a private message, deserves deep suspicion. Independent reviews can add useful context, but even a page full of glowing reviews can’t prove on its own that a lender is trustworthy.
Responsible Borrowing and Financial Planning
Before accepting any credit, it helps to be completely clear about what the money is for and whether savings or another arrangement could cover it instead. A fridge that dies in the middle of a heatwave, taking the week’s groceries with it, is a genuine emergency. A last-minute weekend away with friends is a very different kind of decision. Borrowing works best when it’s built around what can realistically be repaid, not around the biggest figure a lender is willing to offer.
A practical budget covers essential household costs, existing debts, emergency savings and the new loan payment. If repaying the loan would mean cutting back on food, falling behind on rent or borrowing again to keep up, the loan may cause more strain than it relieves. A loan taken to fix one problem shouldn’t quietly create three new ones by the end of the year.
Clear records of payment dates and remaining balances make it much easier to stay in control. A simple reminder on a phone calendar, set a few days before each due date, can prevent a great deal of stress and the occasional late fee. If money becomes tight, contacting the lender early often brings more options than waiting until a payment has already been missed. Lenders generally find it far easier to help someone who calls on the first of the month than someone who goes silent for six weeks.
Conclusion
Fast online lending can be a genuinely convenient way to explore credit, especially for people who prefer to handle their finances from their phones. Speed alone doesn’t make a loan secure, affordable or right for someone’s situation, though. A quick yes is only good news if it’s the right yes.
By checking lenders carefully, guarding personal information, comparing total costs and being honest about what can be repaid, borrowers can make far better-informed decisions. Responsible borrowing brings together the ease of digital tools and the patience of careful thinking, so that access to credit supports real needs without leaving a trail of avoidable problems behind. The best loan isn’t simply the fastest one. It’s the one that still feels manageable on the day the final payment goes through.